Share
ABS Wage Price Index: 79% of Australian jobs below 4% rise as FWC review looms
08/19/2026
7 min
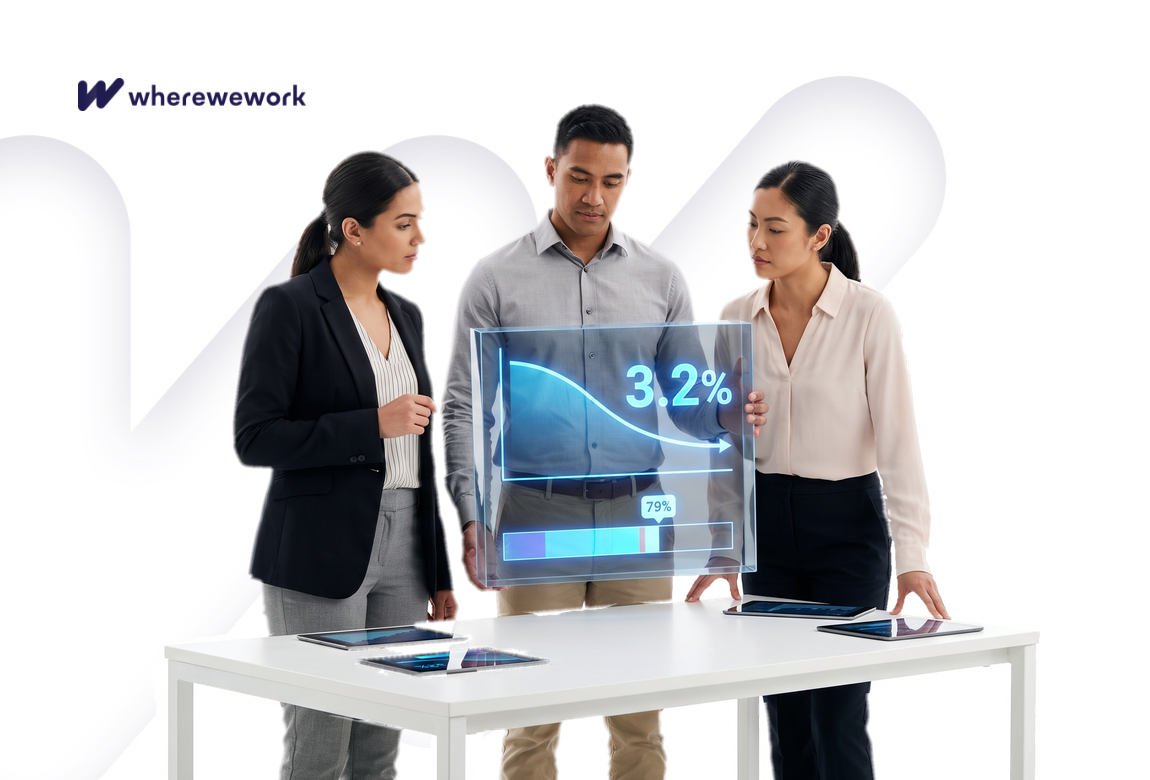
If your last pay review landed somewhere in the 3% range, you are squarely in the Australian mainstream. The Australian Bureau of Statistics (ABS) Wage Price Index (WPI) for the June 2026 quarter shows annual wage growth settling at 3.2%, with 79% of jobs recording an annualised rise below 4%. That single figure has direct consequences: for employees heading into a pay review, it reframes what a strong outcome looks like; for HR and reward teams, it challenges merit-matrix assumptions that were calibrated to a different distribution.
The ABS reported that the WPI rose 0.8% in the June quarter and 3.2% over the year. That is a step down from 3.4% at the same point in 2025, and a more substantial fall from the late-2023 peak of 4.3%. Rachael McCririck, ABS head of prices statistics, put the trajectory plainly:
"Annual wage growth of 3.2% is slightly down from 3.4% at the same time last year," said Rachael McCririck, ABS head of prices statistics.
The context is worth holding onto. Wage growth is softer than the post-pandemic high-water mark, but it still sits well above the 2.2% recorded in the December 2019 quarter, before the pandemic rewrote Australian labour-market conditions. In McCririck's words:
"Although we're currently below the late 2023 peak of 4.3%, annual wage growth remains above the 2.2% that we were seeing in the December quarter 2019 prior to the COVID-19 pandemic."
The Reserve Bank of Australia (RBA) has tracked this moderation closely. Its most recent Statement on Monetary Policy flagged that easing wage pressures are consistent with a gradual disinflation path, which makes the June quarter WPI a data point that feeds directly into rate-setting deliberations as much as it informs payroll budgets.
Where the raises actually landed
The 3.2% headline conceals a much sharper story when you look at how raises are distributed across the workforce. The ABS breakdown for the June 2026 quarter shows most Australian workers clustered in a narrow, modest band:
- 4.1% of jobs recorded an outright wage cut.
- 14.2% of jobs had an annualised wage change between 0% and 2%.
- 21.2% of jobs recorded a rise between 2% and 3%.
- 39.5% of jobs recorded a rise between 3% and 4%.
- 14.3% of jobs recorded a rise between 4% and 6%, down from 17.8% a year earlier.
- 6.7% of jobs recorded a rise above 6%, down from 7.3% a year ago.
Add those bottom four buckets together and the picture sharpens: 79% of jobs recorded an annualised wage change below 4%. That is up from 75% in the June 2025 quarter, and it is the largest share of sub-4% raises since 84% in the June 2022 quarter.
"The decline in the share of jobs with larger wage rises has contributed to slower wage growth overall," McCririck said.
The top of the raise distribution is thinning. Fewer workers are landing 4%-plus rises, and that compression is what is pulling the national average lower. For the Australian Council of Trade Unions (ACTU), which has consistently argued that wage growth needs to outpace inflation to restore living standards, the continued moderation in the upper tail of the distribution is a live concern heading into the next Fair Work Commission (FWC) annual wage review cycle.
The public-private split, now six quarters running
Equally significant is the split between sectors. Public sector wages grew 3.4% annually in the June quarter, outpacing private sector growth of 3.1%. That gap has now persisted for six consecutive quarters, which is a genuinely long run in wage-cycle terms and no longer looks like a catch-up effect.
The ABS points to enterprise agreements as the structural mechanism behind the public sector's edge:
"Rises paid to state government public service jobs were the main driver of public sector growth, supported by scheduled rises paid under the existing APS-wide enterprise agreement for Commonwealth employees," McCririck said.
Enterprise agreements, struck under Part 2-4 of the Fair Work Act 2009 (FW Act), lock in scheduled pay rises for multi-year terms. State government departments in New South Wales, Victoria and Queensland have all settled agreements in recent years with embedded annual increments, which means those workers receive predictable rises regardless of what happens to private-sector sentiment or firm-level budgets. Private sector employees, by contrast, are more exposed to individual bargaining and employer capacity constraints, both of which have tightened as business conditions have moderated through 2025 and 2026.
For employees: what a 3.2% market means for your next raise
Heading into a pay review, you are negotiating in a market where a 3% to 4% rise is now the modal outcome. That is not a reason to accept less than your role is worth. It is a reason to prepare the conversation differently.
Three practical shifts worth considering:
- Anchor on current data, not last year's outcome. The 4%-plus band shrank from 17.8% to 14.3% of jobs in a single year. If your manager is benchmarking against the broader market, it is worth asking which market they mean: the 2024 one or the 2026 one. A salary benchmark built on verified, current pay data gives you a defensible number for that conversation rather than a feeling.
- Factor in the sector gap. Private-sector employees have trailed public-sector counterparts for six consecutive quarters. If you are in private enterprise, the WPI data suggests that moving into an enterprise-agreement-covered role, whether in the public service or in a heavily unionised private sector function, may deliver more compound pay growth than staying put and negotiating incrementally.
- Be clear about what breaks the 4% ceiling. Only 6.7% of jobs received rises above 6% this quarter. Those rises are possible but rare, and they are typically attached to a promotion, a retention counter-offer, or a substantive change in role scope. Breaking above the 4% mark is more often a role conversation than a pure pay negotiation.
One figure that often gets underweighted: 4.1% of jobs recorded an outright wage cut in the June quarter. Nominal cuts are still uncommon, but they are not zero, particularly where variable pay, bonus structures, or organisational restructures are in play. If a significant share of your total compensation is bonus-loaded, it is prudent to model the downside scenario as carefully as the upside.
For HR: recalibrating budgets when the upper tail thins
For HR and reward teams, the June quarter data reframes two questions that typically get worked through in separate planning conversations: what should the salary-increase budget be, and how should it be distributed across the workforce?
The distribution question is the one that has shifted most sharply. A year ago, roughly one in four jobs pulled a raise above 4%. Now it is closer to one in five: 14.3% between 4% and 6%, plus 6.7% above 6%, for a combined 21%. If your merit matrix still allocates budget on the assumption of a wider upper tail, it is out of step with what competitors are actually delivering. The Australian HR Institute (AHRI) has noted in its workforce benchmarking guidance that merit-matrix recalibration is one of the most common gaps between reward policy and market reality in cooling wage environments.
Three areas worth stress-testing before the next planning cycle:
- Retention risk for high performers. With sub-4% now the norm for 79% of jobs, a targeted 5% to 6% rise for your top decile of talent is a smaller premium over market than it might appear in a merit matrix. Model the full cost of losing a critical hire against the cost of a differentiated increase, not against a whole-of-workforce average.
- New-hire versus incumbent parity. In a 3.2% annual market, incumbents drift below new-hire salary rates faster than the headline figure suggests, because posted salaries reflect current market pricing while incumbents carry the compounded effect of two or three years of below-inflation adjustments. Running a pay equity audit before your next hiring wave, rather than after, gives you time to correct the gap without a crisis trigger.
- Enterprise-agreement benchmarking. If you compete for talent with public sector employers or EA-covered private sector organisations, the 3.4% versus 3.1% gap is not a rounding error. Compounded over three years, that differential builds into a meaningful base-pay difference that shows up in offer-acceptance rates and in the tenure data of roles where candidates have options on both sides.
The budget-setting conversation for the 2026-27 planning cycle benefits from moving away from a single company-wide percentage toward a shaped distribution: what proportion of the workforce sits in each raise band, and does that shape actually support the retention and hiring outcomes the business needs? HR leaders operating under National Employment Standards (NES) obligations, including the right to request flexible working arrangements and other minimum entitlements under Part 2-2 of the Fair Work Act 2009 (FW Act), should also consider whether non-pay elements of the employment value proposition can offset the narrowing room in base salary budgets.
What to watch over the next quarter
Two signals will indicate whether 3.2% represents a floor or a stepping stone to further softening. The first is what happens to the 4%-plus share of jobs. If it keeps contracting, the modal raise band drifts toward 2% to 3%, and the negotiating environment tightens further for everyone. The second is whether the public-private gap widens or narrows. Six quarters of consistent outperformance by the public sector is a pattern, not a blip; the September quarter release will confirm whether enterprise-agreement pipelines are structurally outpacing private bargaining over the medium term, or whether private sector catch-up is beginning.
The FWC's next Annual Wage Review decision, which sets the national minimum wage and flows through to Modern Award minimum rates, will also shape the floor of the distribution. In prior cycles, the FWC has considered WPI data alongside CPI outcomes and labour-market conditions when determining the percentage uplift. With annual wage growth at 3.2% and the upper tail of the distribution continuing to thin, the shape of the June quarter data is directly relevant to that deliberation.
For now, the operating reality is consistent on both sides of the employment relationship. The wage market is cooler than it was at the 2023 peak, but it has not stalled. The room to negotiate above 4% still exists, and the data shows 21% of jobs managed it this quarter. Getting into that cohort takes more targeted preparation than it did eighteen months ago, whether you are the one asking for the rise or the one deciding whether to approve it.
Share
What I read is worth it:
Read all the articles about
HR Metrics Workforce planning Statistics Negotiation Labour market Career planning Editorial EconomicArticle written by:
 wherewework.com
Comments
0 comments
No comments! Be the first to comment on this article!

Access your account and add your comment
HR Metrics
Subscribe to the Newsletter
Read articles of interest from wherewework.com contributors
